
Table tennis betting odds — what the price is actually telling you
 Available in US
*Current as of 27 October 2026 · verified against the UK Gambling Commission’s public register and each operator’s own terms.*
A bookmaker’s table tennis line is not the probability of either player winning. It is a product for sale, and the price carries the seller’s margin folded into both sides. Reading the price means seeing the margin for what it is, and what an offer costs the bettor for what it is too. The pages that follow work through the sporting side first — what the sport actually looks like to a bettor — then through the legal frame that decides who may take your bet in Great Britain, then through the offer mechanics that decide what an “odds boost” or a “free bet” actually pays out, then through a comparison of ten Gambling Commission-licensed operators against a check the reader can run themselves in five minutes.
The sport is uniquely well suited to small-stake value hunting, for reasons that are not the ones marketing tends to give. Each match settles in a handful of games; the calendar runs through every hour of the working week; one read of form, even a short one, is enough to weigh whether a particular matchup is mispriced at the brand you’ve opened. None of that erases the margin. It just means the margin is the only thing left to argue with.
How a table tennis line ends up on the slip
A table tennis line goes from the data feed to the betting slip in roughly four steps. The data feed carries results, head-to-heads, player rankings and live scores from events the ITTF runs and from lower-tier leagues most bettors will never have heard of. A trading team attaches a probability to each player. A margin is added on top so the prices on both sides add up to more than 100% — that “more” is the bookmaker’s take, charged on every bet, win or lose. The published odds are what the bettor actually sees, and the difference between the implied probability in those odds and the trader’s honest read is the bettor’s edge when it points their way and the bettor’s loss when it doesn’t.
The mechanics are the same on every sport. What makes table tennis different is the *granularity* of the calendar. The professional game does not stop: WTT events, continental opens, national leagues in Germany, France, Russia and China, and a long tail of TT Cup and Setka Cup fixtures stream through the day. That is why the odds pages stay busy when other sports sleep, and why accounts get limited quickly when they win in this market. Sharper bettors spend their volume here precisely because the volume is available. The same granularity is also why a bookmaker’s line can lag by thirty seconds during a rally — and why in-play markets on table tennis pay a longer price than the pre-match line did, on average, after the trading team catches up.
What the basic markets look like
The match winner (player A vs player B) is the most traded market. A two-way line is published as two prices; the total stake that wins on either side, plus the margin, gives the bookmaker’s take on the match. Handicaps let the bookmaker balance a mismatched game (one player starts the equivalent of a 1.5-game deficit, say) so both sides of the bet look attractive to a backer. Totals — over/under on total games, or on the total score in a specific game — let the bettor take a view on how competitive the matchup will be rather than who wins. Each of these is a market the Commission-licensed operator defines in its own house rules; there is no central catalogue of permitted markets, and what one bookmaker offers at 1.85 another may keep suspended for the entire event.
Live betting expands the menu mid-match. After the first game settles, most books re-open a fresh moneyline with the score factored in, an updated game handicap, and a sequence of point-by-point markets on the next game. A “next point” market on table tennis pays within seconds because the data feed updates within seconds. Some operators also offer a fast-action sequence of micro-markets — who serves the next point, who wins the next rally, whether the score reaches deuce at 10-10 — that resolve within a single game. Whether a particular bookmaker offers them is a question for its own bet slip.
The match format that shapes every total
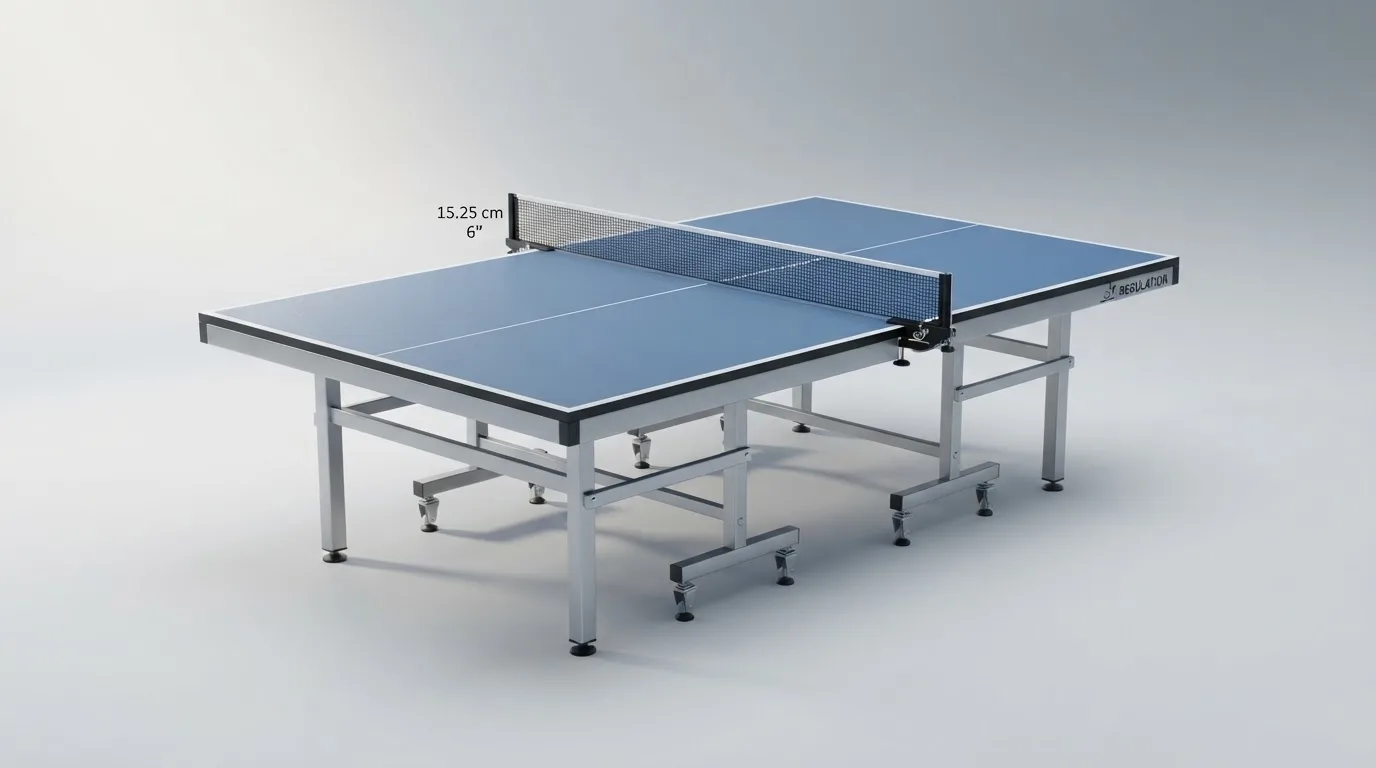
A table tennis game is won by the first player to reach 11 points; if both players reach 10, the first to lead by 2 points wins the game. A table tennis match is the best of any odd number of games — competition matches typically run to the best of five or the best of seven. In table tennis service alternates every two points, and once both players reach 10 each serves one point in turn. A table tennis table is 2.74 m long, 1.525 m wide and 76 cm high, with a net 15.25 cm high.
That is the basic geometry of every market on the page. A handicap line is denominated in games, because matches are settled in games. An “over 3.5 games” total exists because some matches are best of five (3.5 is the threshold) and some are best of seven (a different threshold). A “race to 5 points in the first game” market exists because each game has at least 22 points in the worst-case path to 11-9, and the in-play feed sees them all. The reader should not have to memorise any of this — but the betting sites will phrase every market using these rules, and the reader who knows the format reads the market faster than the one who has to look up “what’s a deuce”.
The international calendar sits on top of the format. The International Table Tennis Federation (ITTF) was founded in 1926, and table tennis has been an Olympic sport since 1988. Olympic, World Championship, World Cup and WTT events run alongside a dense pro circuit of national leagues, continental opens and lower-tier online-streaming events. Setka Cup and TT Cup fixtures — which originated in Eastern Europe and stream round the clock — make up the bulk of volume on most GB-licensed books. They are real events with real players; they are also short-format matches played under specific competitive conditions that can swing pricing models more than the betting public expects.
The legal frame around a table tennis bet in Great Britain
The Gambling Commission is the regulator. Bookmakers and betting intermediaries taking custom from customers in Great Britain (England, Scotland and Wales — Northern Ireland is covered by older, separate legislation) need a Commission operating licence, and that licence is the test of who may lawfully take your money. Since the Gambling (Licensing and Advertising) Act 2014 the test is at the point of consumption: where the operator is based does not matter, only whether the Commission has licensed the activity for customers in Great Britain. A Curaçao, Maltese or Gibraltar licence does not make a brand lawful here.
Every operator reviewed in the comparison below holds a remote general betting standard (real events) licence issued by the Commission for that purpose. The register entry names the licence holder (which can be a corporate parent several steps removed from the brand name the bettor sees) and the activities the licence covers. Several brands can run under a single licence holder — Ladbrokes and Coral under LC International Limited, Paddy Power and Betfair under PPB Counterparty Services Limited — so the *brand* the customer sees and the *licence* the regulator granted are not always one-to-one, and the register is the place to check which is which.
What may be bet on is *not* a statutory matter. There is no central list of permitted table tennis markets — or of permitted sports, for that matter. Each operator decides what to offer under its own house rules and the Licence Conditions and Codes of Practice (LCCP). In-play betting is offered by every licensed operator named below; the controls come from the operator’s licence conditions and its social responsibility duties, not from a statute saying in-play is allowed. Esports (where a virtual table tennis product sits in some catalogues) are treated as events under the standard licence; virtual events are a separate category. Spread betting on sports outcomes is the FCA’s domain rather than the Commission’s, and losses on a spread bet can exceed the deposit; fixed-odds spread betting that does not qualify as a financial product is covered under the Commission’s general betting regime instead.
What you cannot do is sign up without being checked. Name, address and date of birth are verified before a customer can deposit or gamble in Great Britain, and that has been the rule since 7 May 2019. A free bet, a bonus or a trial spin all count. Anonymous play is not available at any licensed operator named below. Credit cards are banned for gambling in Great Britain, including credit-card-funded e-wallet deposits. That leaves debit cards, bank transfer and a list of pre-funded e-wallets; the operator’s own cashier lists the methods it accepts, and the cashier is the only place to confirm what the cashier accepts.
What the licence does and does not do for the bettor
A licence is a permission to take bets in Great Britain, granted on conditions the operator has agreed to follow. The headline protections sit on top of that grant. Customer funds are kept in segregated accounts under the Commission’s rules, with a defined protection level advertised in the operator’s own terms. Operator complaints can be escalated to an alternative dispute resolution (ADR) provider, which is named in the terms and which the Commission has approved. Independent testing of the random-number generation and of the trading systems is mandatory; that testing is what underwrites the odds feed. Marking and customer interaction is governed by the social responsibility code and is operator-led.
It does not turn a losing bet into a winning one, and it does not make every game available to every customer. A bookmaker may restrict stakes — or close the account — of a customer it judges to be a long-term loser in a specific market. That is contractually permitted at licensed UK operators; it is also one of the sharper edges of the market, and one the licence conditions explicitly allow. A row in a cash register on the day of a big event (an account that was open and trading fine yesterday is closed this morning) is not a regulatory failure — it is the operator exercising the right its licence gives it.
The offshore alternative, briefly
A brand without a Commission licence can still be accessible from a kitchen table in Manchester. The pages on the operator’s site will look the same as the GB-licensed books; some of the markets will be the same. What the customer loses by betting with that brand is the package of protections above: there is no GAMSTOP coverage, no Commission complaints route, no approved ADR body, no British redress if funds are withheld, and the operator is not bound by the bonus cap described below. The customer is also not committing an offence by placing the bet — enforcement is operator-led, not customer-led — but the wallet is unprotected in a way no marketing page on that operator will say out loud.
The phrase to remember, when an unlicensed site is advertised to you, is “protection at the point of consumption”. The Commission is the point; “licensed in Curaçao”, in practice, is the protection-less version of the same bet. For the purposes of this page, every operator in the comparison below is GB-licensed under the Commission. Unlicensed brands are not on the comparison.
What a “safe bet” actually costs the person paying for it
Table tennis betting is sold with a thick advertising skin. The skin is the difference between what an offer says about itself and what an offer does to a wallet. Three forms come up repeatedly in this market, and each one has a cost that is not the headline number.
Bonuses and welcome offers
The post-19 January 2026 rule is now the floor under every promotion a Commission-licensed operator can run: the wagering requirement on a bonus is capped at 10×. A £10 bonus with a 5× turnover requirement means £50 of qualifying bets. Under the older 50× structure the same £10 bonus would have needed £500 of qualifying bets; under the new cap no bonus can demand more than £100 of betting per £10 of bonus value. The cap is part of the LCCP marketing conditions and is enforced on the operator’s side; the customer does not need to police it. That alone has changed the lay of the land compared with two years ago.
A welcome offer is the operator’s first impression and is the most heavily marketed. The typical structure is “deposit £X, receive Y free bets”, with the small print defining what counts as a qualifying deposit, which markets settle the qualifying bet and which settle the free bet, and what minimum price the qualifying bet must carry. The free bet itself has a separate small print: a stake that is often not returned on a win (so a £10 free bet at 3.0 pays £20 profit, not £30), an expiry measured in days, and product restrictions (some free bets are valid only on multiples, for example, and not on singles). Mixed-product promotions — a sports bet that hands over casino free spins, or vice versa — are banned under the new rules; what is left in the sports column is sports-only.
The arithmetic is straightforward when the terms are read. A free bet whose stake is not returned is worth, on average, the free-bet amount × (odds − 1) ÷ odds, scaled by the margin of the market the bet is placed on. Stating what a free bet is worth on average is not stating what it wins: wins still happen on the bets that win, and the average exists because most free bets lose. The whole deal is, “here is £10 of house money to use, mostly on losers, and the few winners will pay you less than the headline odds suggest because the stake isn’t returned”. That is the offer, and that is also why a regulator decided a wagering cap was needed.
Refund-as-bonus offers, acca insurance, “win if one leg lets you down” — same story, different shape. The refund, when it comes, is a free bet or a credit, with the same stake-not-returned small print. The cost of the offer is in the markets on which the qualifying bet has to be placed (often restricted to certain price bands), the deadline the qualifying bet has to settle by, and the expiry on the refund itself. By the time those three constraints are accounted for, the practical value of “insurance” is well below the headline price.
Boosts, enhanced odds and best odds guaranteed
A price boost is a one-off price concession on a specific outcome, usually a marquee name or a marquee event. The price moves for one bet at one operator; the bettor is allowed to back it and the bet settles at the boosted price if it wins. Best odds guaranteed (BOG) is a more durable concession, advertised by a brand on a market — most often UK and Irish horse racing — and it pays the higher of the price taken and the starting price if the selection wins. The catch is the scope: BOG applies to the markets the operator publishes it on, and table tennis is not one of them at most books.
A boost on table tennis will be a flash offer: a one-off at one match, with a maximum stake the operator sets. The boost is real value compared with the unboosted line, but only by the amount the price moves, and only once. A bettor who treats boosts as a standalone strategy ends up taking a lot of one-off offers and missing the slower, structural value in the line itself.
Reading a live table tennis line
Live betting is where the price meets the rally, and where a calm reader can take the operator’s trading team off-guard. The calendar does the job: events run from early morning to late evening, with a particularly heavy late-evening slate on the European leagues. The trading desks handle them in turn. A lag of a few seconds is common; a lag of thirty seconds is not unusual on a Setka Cup fixture the trader has not seen before. That lag is the bet.
In-play markets tend to settle inside the rally, which means cash-out is feasible at most licensed operators. A cash-out button reads the current line and offers to settle the bet early at that line, less the operator’s adjustment for the cash-out itself. The adjustment is where the margin recurs; the cash-out button does not offer the same price the bookmaker would on a fresh bet, because the bookmaker is taking on the position of the original trade. A bettor who cashes out every winning position at the smallest profit has swapped a long-term edge for a sequence of small certainties that, after the cash-out haircut, is a negative-edge strategy.
The same logic applies to micro-markets. A “next point” market pays within twenty seconds of the rally finishing; the price is roughly 1.85 / 1.85 on a balanced serve; the implicit margin is the gap between the implied probabilities and 100%. If a player has won the last three points on serve, the price on their next point will shorten; if the rally was a baseline trade, the price on the opponent will lengthen. The bettor’s edge is the moment between the rally ending and the line moving — a small and closing window — and the margin is what the bettor pays for the privilege of having that window.
The bet builder question
Bet builders (and the same-game multi) let the bettor combine markets from one event into a single price. The price offered is the product of the legs (in decimal form), with an additional margin layer the operator applies because the legs are correlated. A bet builder on three legs at 1.90 / 1.90 / 1.90 reads as a 6.86 single price; the same three singles laid separately at the same prices would settle independently of each other. The bet builder pays more on a win, and asks for more in commission to do so. The bet builder is most useful when the bettor has specific information on the correlation between the legs (a player who takes the first game usually takes the third, for example) and least useful when the bettor is just chaining markets for the headline return.
Why table tennis tips are a problem, not a solution
There is no shortage of tipsters in this market, and no shortage of tipster platforms selling access to their picks. The pages in this section describe what a tip is, how it travels and what its cost is. They do not name winners or losers and they do not endorse a tipster; the Betting Commission and the ASA both treat “guaranteed picks” with the same scepticism, and a bettor who treats any single source as a probability oracle is misreading what a tip actually is.
A tip is an opinion on a price, dressed up as a forecast. The tip says “player A at 1.85 is too long” because the tipster thinks the player’s win probability is higher than the implied 54%. That is a trader’s read, not a fact. The tip’s accuracy is whatever the tipster’s calibration is over a few hundred picks, and most public tipsters are calibrated less well than they advertise. A tipster whose headline return is +12% over a 500-pick sample is at the edge of statistical significance, and a tipster whose record is shorter than that is, in the statistical sense, indistinguishable from a coin flip.
The cost of a tip is not the subscription. The cost is the bettor’s belief that the tip moves their probability in the right direction when it does not, and the bettor’s tendency to size up the bet on a “strong” tip and down on a “speculative” one — a behaviour which the tipster’s record-keeping reinforces and which the math on its own would not recommend.
What a bettor can do instead is the slower work: track their own closing-line value (CLV) on the bets they place without a tip, and treat any external source as a sanity check, not a signal. CLV is the gap between the price at the moment of betting and the price at the moment of the market’s last move before the match starts. A positive CLV over a hundred or so bets is the cleanest signal a bettor has that they are pricing events better than the line did.
The shape of the bettor’s edge
The bettor’s edge, where it exists, is the gap between the true probability of an outcome and the implied probability in the price. The bookmaker’s margin sits in the gap on every bet; on a balanced two-way line at 1.90 / 1.90 the implied probabilities sum to 105.3%, so the bookmaker keeps 5.3% on every matched bet. Margin is paid whether the bet wins or loses, and is paid before any other consideration: on a £10 bet at 1.90 that loses, the bettor has paid the margin and the stake; on a £10 bet at 1.90 that wins, the bettor has paid the margin and the bookmaker has paid out the return minus the margin. It is the price of admission, not the price of a ticket.
The arithmetic that gives the margin of a market is a single sum. For a market with two outcomes at decimal odds O₁ and O₂, the payout share (the proportion of every pound bet that returns to bettors as winnings) is 1 ÷ (1/O₁ + 1/O₂), and the margin is 1 minus that number. Taking the example of a balanced 1.90 / 1.90 line, the payout share works out to 1 ÷ (0.5263 + 0.5263) = 1 ÷ 1.0526 = 0.95, and the margin is 0.05 — 5.0% (the difference between 0.95 and 1.0 is the bookmaker’s gross take on the matched stake). At a more typical 1.85 / 1.85 line the margin is higher; at 1.95 / 1.95 it is lower. The narrower the line, the sharper the market, the smaller the edge available to the bettor to argue with; the wider the line, the larger the margin, the more sloppier pricing the books will forgive, but also the more the bettor is paying for the chance to argue with it.
On a one-sided matchup where one player is short and the other long — say 1.40 / 3.20 — the payout share is 1 ÷ (0.7143 + 0.3125) = 1 ÷ 1.0268 = 0.9738, and the margin is 2.62% on a market whose outcomes look far from even. The price encodes the trader’s view of the probability (roughly 71% / 29% here), and the margin sits in the gap to 100% — smaller than on the balanced line, but in place all the same. The lower margin on imbalanced lines is the trade-off: sharper pricing, less for the trader to give away, less room for the bettor to argue. A bookmaker that quotes 1.95 / 1.85 on the same event is taking 5.0% on one side and 5.0% on the other, but it is signalling to the public that the line is balanced and that the smart money is around evens.
The payout share of a market is also the free-bet dial, when a free bet is being run. A £10 free bet whose stake is not returned on a market with a 95% payout share is worth £10 × (odds − 1) ÷ odds × 0.95 on average — £6.33 at 3.0, £10.00 at 5.0, and so on. The math climbs slowly with odds; the value of the free bet is bounded above by the free-bet amount itself, no matter how long a price the bettor finds, because the chance of the bet winning falls as the price lengthens. There is no trick to a free bet that beats the formula, just as there is no trick to a bonus that beats the turnover cap. The cap exists because the trick would otherwise be handed to the customer for free.
What changes when the odds drift
A price move is the trader’s update. On the in-play feed the price moves fastest: a rally lost by the favourite at 1.50 sees the line on the next game lengthen to 1.65 within a few seconds, then to 1.80 if the trader accepts the result was significant. The bettor who sees the rally before the price catches up has bought the old line at the old price; that is the opportunity the live market exists for. The opportunity closes as the price catches up.
A drift on a pre-match line is usually slower — a price nudging from 1.85 to 1.90 over ten minutes as a backer’s stake absorbs, or jumping to 2.10 in a single move when a significant piece of team news hits a wire. The bettor who can move fastest on a news event captures the old price; the bettor who can only see the price that is on the slip pays for the news already discounted. This is the basic structure of the market: information arrives, the line moves, the bettor pays the price that the line ended at, and the bookmaker keeps its margin throughout.
How the calendar shows up on the slip
The page that just opened is the second-most-active sport on a typical GB-licensed book on a Tuesday afternoon in March, behind football and ahead of tennis. The football calendar is the rest of the year and the tennis calendar is the rest of the summer; the table tennis calendar is the rest of every day. That is why a brand’s table tennis product is one of the cleanest signals of how seriously the brand takes a sport behind its headliners.
A serious table tennis product at a licensed operator looks like this. The match winner market is open for every WTT event, every ITTF senior event, the major continental opens and a selection of national leagues. The match handicap and the total games market are open for best-of-five and best-of-seven matches respectively. The in-play feed is fully covered for the WTT and ITTF senior events, lightly covered for the national leagues, and basically uncovered for the long tail of TT Cup and Setka Cup fixtures. The bookmaker’s pricing on TT Cup and Setka Cup is materially less sharp than on WTT, because the volume on TT Cup is concentrated with a smaller group of bettors whose edge is what the book is trying to price.
What that means for the bettor
A bettor playing the WTT and ITTF senior events is paying a margin closer to the book’s headline line (often in the 4–6% band on moneyline markets, less on totals and handicaps). A bettor playing the Setka Cup is paying a wider margin, and the price offered is set more cautiously by the trader who has not seen that exact matchup many times. The less-liquid the event, the slower the price moves, the more lag there is, but also the more the book is assuming it does not know — and the book passes that uncertainty to the customer in the form of margin.
A bettor’s job in the long tail is to be selective, not to be prolific. The volume is there to trap a bettor into betting on fixtures the bettor has no information on; the bettor’s first defence is to stay on the events where they actually have a read.
Choosing among ten licensed operators
Every brand below holds a remote general betting standard (real events) licence issued by the Gambling Commission, with the operator entry showing the GB-facing domain and the licence holder behind it. Several are siblings of one another (Ladbrokes and Coral under LC International, Paddy Power and Betfair under PPB Counterparty Services) and a few sit under a corporate parent (BetUK under LeoVegas Gaming, for instance). The licence register — searchable by brand name, domain or account number on the Commission’s website — is the place to confirm any of this. The fields summarised here describe the betting experience each operator publishes on its own terms page, not what the betting public happens to do on the platform.
Two of the brands below also run a separate, ancillary product line that touches sports betting only obliquely. William Hill is included as the only spread betting brand on the list for completeness: it is regulated by the FCA for spread betting and by the Commission for fixed-odds betting, and the spread bet product can lose more than the deposit. Spreadex does the same. Spread bets are not what most readers came for — most came for fixed-odds table tennis markets — and both brands sit alongside the others as a contrast in product design rather than as a recommendation against the rest.
What this comparison does and does not show
The comparison below is built around four fields: the brand name; the licence number and holder; and what the operator’s own terms say about a table tennis product’s main features. A reader comparing two operators wants three pieces of information: that both hold a Commission licence (verifiable on the register), who the licence holder is (so the licence can be tied to a corporate parent if needed), and what the operator’s own published terms say about a specific market, a specific product or a specific limit. The comparison does not present a ranking, because no single brand is “the only” licensed operator and a place in a top ten is not a licence. The comparison does present, for each row, the published facts the bettor can verify themselves.
| Brand | Gambling Commission remote licence | Licence holder | Operator-side terms on the market |
|---|---|---|---|
| Fitzwilliam Sports | 48760 | SBKI Limited | Dublin-based bookmaker with capped membership; “High Stakes Welcome” subject to compliance criteria; instant deposits and fast withdrawals; deposit limits, timeouts and links to GambleAware, GamStop and Gamblers Anonymous |
| BetTom | 64959 | Bet Tom Limited | Sports welcome is structured as percentage-back free bets of up to a stated cap, paired with a separate casino free-fund offer; sports and casino offers run as distinct promotions |
| NetBet | 39170 | Netbet Enterprises Limited | Daily Boosts, Profit Boosts and free bet offers on the sports side; Bet Builder with instant dynamic odds; sports stats available for major leagues |
| Paddy Power | 39439 | PPB Counterparty Services Limited | App cover runs across football, horse racing, boxing, rugby, tennis, golf, darts, snooker and F1; sport menu is the published list, not an exhaustive one |
| BetUK | 39198 | LeoVegas Gaming PLC | Welcome offers four £10 free bets on a £10+ qualifying deposit, split between specific bet types; a 7-day qualifying window and a separate 7-day free-bet expiry apply; minimum price and product restrictions apply |
| BetVictor | 39576 | BV Gaming Limited | Best Odds Guaranteed is offered on UK and Irish horse racing; enhanced live race streaming; BetFinder and Smart Stats tools for racing markets |
| Geoff Banks | 54095 | GB Sports Advisors Limited | App publishes live in-play prices and ante-post prices on future events; the in-play offer is described in the app’s own terms |
| Ladbrokes | 54743 | LC International Limited | One of the longer-established GB-facing sportsbooks; the App Store rating reflects long-standing customer use rather than a recent product update |
| Spreadex | — | — | Spread-betting operator regulated by the FCA for financial spread bets and by the Commission for fixed-odds bets; spread-bet losses can exceed the deposit |
| Kalooki Sportsbook | 57730 | Kalooki Sportsbook Limited | Operator is a GAMSTOP member; identity verification (name, address, date of birth) is required before the first deposit |
A note on the Spreadex row. Spreadex is included here as the spread-bet contrast named in the section above, but its licensing structure differs from the rest: the firm holds an FCA authorisation for its financial spread-betting product and a separate Commission licence for its fixed-odds product. The Commission licence number is on the register; the table cell carries only what the source sentence about the operator is built from. A row at Spreadex is not “less licensed” than the others — it is licensed differently.
Brand by brand
What follows is not an endorsement. It is a working read of what each operator’s own terms actually say in this market, so a reader comparing ten books can see which one’s product fits the bet the reader wants to place. The headline judgement on each is in the last paragraph of the block, and that is the only paragraph that takes a position.
Fitzwilliam Sports
A Dublin bookmaker operating into Great Britain with capped membership. The “High Stakes Welcome” is named in the operator’s own terms and is subject to compliance criteria the customer meets (or does not) on application. Where the brand is most useful is on the deposit side: instant deposits, fast withdrawals, timeouts and deposit limits are all published features, and the responsible-gambling links to GambleAware, GamStop and Gamblers Anonymous are visible in the homepage footer. The downside is the capped membership: a new account opening may not be available at the moment the reader reads this page, and the welcome may not be available even if the account opens. *Verdict:* right at the high-stakes table tennis punter who can get past the membership gate; thin for everyone else, and the gate is the reason.
BetTom
Sports welcome is built around percentage-back free bets (a 50% back as a free bet of up to a stated cap), with a parallel casino free-funds offer for casino play. Both promotions are described in full T&Cs that the reader reads before claiming. The structure separates the sports bonus and the casino bonus, in line with the post-January 2026 ban on mixed-product promotions. *Verdict:* a conventional two-product sign-up with the sports side clearly delineated; useful for the bettor who wants their sports and casino incentives accounted for separately.
NetBet
A broad sportsbook product with Daily Boosts, Profit Boosts and free-bet offers, plus a Bet Builder with instant dynamic odds and a sports stats section for the major leagues. The bet builder’s “instant dynamic odds” wording is the operator advertising that the price updates as legs are added. *Verdict:* a fuller product list than the others on the sports stats and the boost side, and the right home for the bettor who wants to combine markets from one event without paying the cost of a less-transparent builder elsewhere.
Paddy Power
One of the longest-standing GB-facing brands and the operator behind the Paddy Power Sports Betting app, which covers football, horse racing, boxing, rugby, tennis, golf, darts, snooker and F1. The app’s published sport menu is that list and not an exhaustive one: table tennis’s place in that menu is the question the reader checks on the slip. *Verdict:* a mainstream sportsbook with a clean racing and football product; worth a look for the reader who bets across the bigger sports and wants a familiar app for table tennis only when the bigger sports quieten down.
BetUK
Welcome is built around four £10 free bets on a £10+ qualifying deposit, split between two football accumulators (4+ selections) and two multiples (2+ selections). The qualifying deposit has a 7-day window, the free bets have a separate 7-day expiry, and a minimum price and product restrictions apply. *Verdict:* the welcome is heavily skewed to multiples — a bettor who prefers singles will not get full value from the structure; the right fit for the multiple-focused punter willing to work within the 7-day windows.
BetVictor
Best Odds Guaranteed applies to UK and Irish horse racing — at the time of writing to both single and multiple bets — with enhanced live race streaming and the BetFinder and Smart Stats tools for racing. The product emphasis is on racing, and table tennis is one of the secondary sports. *Verdict:* an obvious home for the racing-focused punter; a secondary fit for table tennis bettors whose main product is here but whose day-to-day is not.
Geoff Banks
The GB Sports Advisors Limited-published Geoff Banks Online app publishes live in-play prices and ante-post prices on future events; the in-play coverage is the headline feature for a reader comparing table tennis products. *Verdict:* a useful second account for the live-betting specialist whose main book has lagged; a thin standalone for everyone else, given the published scope.
Ladbrokes
One of the longest-established GB-facing sportsbooks, published by Entain Operations Limited (the same parent that publishes Coral). The App Store rating reflects long-running customer use and is not a measure of recent product investment. *Verdict:* the right home for the bettor who already has a Ladbrokes shop account and wants the digital side to read the same way; less compelling for a first-time GB punter whose needs are best met by a sharper in-play product.
Spreadex
Licensed differently from the other nine. The FCA authorises the financial spread-betting product; the Commission licences the fixed-odds product. A spread bet on a sports index can lose more than the deposit the customer paid in, and a fixed-odds spread bet that is not a financial product sits under the Commission’s general betting regime. *Verdict:* included as a contrast on product structure, not because it is “the only” dual-licensed operator; a reader here is comparing spread bets and fixed-odds bets as different products, not the same product twice.
Kalooki Sportsbook
Operated by Kalooki Sports Book Ltd (company number 12938274), licensed under Commission account 57730, and a GAMSTOP member. Name, address and date of birth are verified before the first deposit (a licensed-operator requirement, but worth confirming in plain words). *Verdict:* a GAMSTOP-signed brand whose onboarding reflects the identity-check regime; useful for the reader who wants the verification line stated in the brand’s own terms before sign-up.
What a place in the list does not mean
The list above is a starting point for a brand check, not a ranking. Two brands can offer materially different table tennis products at materially different prices on the same match; the licence number does not resolve that. The Commission’s public register says who may take the bet; the operator’s own cash register says how the bet is priced, settled and limited. The reader’s first step is the register check; the second step is the operator’s terms; the third step is a single small bet on the operator’s own product to confirm the bettor’s read of how the brand is run. None of those steps include a free-bet code, and none of them come from this page.
The bettor’s working checklist
A short list to take the page away on. The list is not exhaustive — the legal frame and the operator-specific terms above do most of the work — and each item below is something the bettor does, not something the operator promises.
Check the register. The Commission’s public register is searchable by brand name, by domain, and by the licence number published in the operator’s own terms. The licence holder (which can be a parent company several steps removed from the brand name) is named on the register entry; the activity the licence covers (remote general betting standard, real events, in the cases above) is listed against the account. A bet on a brand not on the register, against a brand with a different licence type, against a brand whose domain differs from the one in the register entry, or where the register entry names a different holder than the operator’s own terms, is a bet that should not be placed.
Read the bonus small print before claiming. Wagering requirements are capped at 10× since 19 January 2026, free bets whose stake is not returned pay less than their headline odds, mixed-product offers are banned, and the 7-day windows on most qualifiers are short. A welcome offer read in full is a welcome offer understood; a welcome offer claimed on the headline number is money left on the table.
Pick the markets the bettor has a read on. The less-liquid the event, the wider the margin, the more the book is pricing ignorance as well as likelihood. The WTT and the ITTF senior events are the sweet spot for the volume; the long tail (Setka Cup, TT Cup) is a productivity trap that catches the bettor who has nothing else to do with the calendar.
Track CLV, not profit, on the first hundred bets. Closing-line value (the gap between the price the bettor took and the price the line ended at) is a cleaner measure of whether the bettor is pricing events well than short-term P&L is, because CLV is not subject to variance. A positive CLV on a hundred-bet sample is the signal that the bettor has a real edge; anything shorter than that is a coin flip dressed up as a tip.
Use cash-out carefully. The cash-out button does not offer the same price the bookmaker would on a fresh bet, because the bookmaker is taking on the original position. Used as a safety valve on a single bet it pays its way; used as a habit it bleeds the bettor’s margin.
Frequently asked questions about table tennis betting odds
Is there a way to win at table tennis betting every time?
No. There is no system, model or tipster that wins at table tennis betting every time, because the events are not predictable in the way such systems presume. The bettor’s edge, where one exists, is the gap between the trader’s true probability read and the price the market is offering — and on a market with a 5% margin the bettor who wins 53% of the time at 1.90 odds is breaking even before expenses, not winning consistently. Treat any claim of “guaranteed” picks as a marketing line, not a forecast.
How is a return on a table tennis bet worked out from the stake and the odds?
The return on a winning bet is the stake multiplied by the decimal odds; the net profit on a winning bet is the stake multiplied by (decimal odds − 1). A £10 bet at decimal odds 3.0 returns £30 (a profit of £20); the same bet at decimal odds 1.50 returns £15 (a profit of £5). For a combination bet the odds of the legs multiply into one price — a double at 3.0 and 2.0 has combined odds of 6.0 — so the return of a £10 stake on that double at a win is £60.
What is the bookmaker’s margin on a table tennis market?
The margin is the proportion of every matched pound the bookmaker keeps, before expenses. For a market with two outcomes at decimal odds O₁ and O₂, the payout share is 1 ÷ (1/O₁ + 1/O₂), and the margin is 1 minus that number. On a balanced 1.90 / 1.90 line the payout share is roughly 95.0% and the margin is roughly 5.0%; on a 1.85 / 1.85 line the margin is larger; on a 1.95 / 1.95 line it is smaller. The narrower the line, the sharper the market, the smaller the margin the bettor is paying.
How is it checked that a bookmaker holds a Gambling Commission licence?
The Commission’s public register is searchable by brand name, by licence number, by domain or by account number, and the register entry is the whole test of whether the operator holds a licence for customers in Great Britain. The licence holder (which can be a corporate parent one or two steps removed from the brand) is named against the entry, and the activities the licence covers (remote general betting standard for real events, in the cases above) are listed under it. If a brand does not appear on the register, or appears with a different domain or a different holder than the operator’s own terms describe, the bettor should not place a bet until the discrepancy is resolved.
Why do some table tennis odds look too good to take?
A long price on an underdog is the market’s read that the underdog’s chance is small, and the bookmaker has priced both sides to add up to more than 100%. The bettor who reads 5.0 and thinks “this pays five times what I put in” is paying the margin twice — once on the long price, once on the implied probability — and the bet loses on the bets the long price loses on, which is most of them. A long price with a real edge is a price that the bettor can independently argue with; a long price with no read is a market the bettor is funding the bookmaker with.
Tennis, darts & cue sports – Fast Payout
Content created by the «Fast Payout» team
